What Smarter Branch Strategies Do for Long-Term Banking Success
Discover how a bank branch optimization strategy improves branch performance, enhances customer access, and supports long-term banking success.
Branch decisions shape customer access, operating costs, and growth for years. As mobile banking expands, physical locations still matter for advice, complex transactions, and local relationships. A network that fits current demand can become poorly placed or too costly as populations shift and customer habits change. Long-term success requires leaders to assess each location as part of a connected portfolio. The work starts by defining what the network must deliver.
A well-defined bank branch optimization strategy helps financial institutions align customer access, operating costs, and growth objectives over the long term. A useful bank branch optimization strategy begins with a clear account of each branch’s purpose, local market, and contribution to customer access. Well-planned bank branch strategies connect local demand, financial performance, and service needs before leaders commit capital. That framework lets decision-makers compare locations on consistent terms, identify investments with a sound business case, and avoid relying on isolated branch results.
Treat Branches as a Portfolio
A branch’s value depends on more than its deposits, transactions, or occupancy costs. Proximity to other sites may mean overlapping customers, identical services, or separate catchment areas. Showing distance and drive times allows leaders to discern whether a bad score indicates the site itself or branch surrounding areas. Customer mapping shows where a consolidation would affect access.
An effective bank branch optimization strategy evaluates each location within the wider network rather than relying on individual branch profitability alone. Locations evaluated in the portfolio should compare their performance to the goals set by the bank, with attention to market size, customer demand, and purpose of service. For example, one branch may conduct routine transactions, while another addresses small businesses or guides customers who require personal assistance. Well-defined roles prevent a single profitability metric from dictating decisions that diminish the network’s reach or capacity during peak times or availability where options are limited.
Test Performance Against Market Evidence
A data-driven bank branch optimization strategy starts with historical performance and compares it with reasonable financial and operational projections. Look at internal performance data that start from a baseline, but one year simply isn’t enough. Look at deposits, service levels, staff costs, lease expirations, and the trend over the recent period in conjunction then look at them against your reasonable projections. This will uncover softness versus permanent underperformance and let you identify which branches need fixing when it’s not an urgent capital decision.
External data can be used to determine if the internal results are valid, for example are the results typical of local conditions, shifting populations, employment hubs, road access and whether further development is planned. These factors can change demand even when branch operations remain constant, so leaders should assess them at a useful local level. Compare each branch’s customer base and service mix with the people and businesses the area can support.
Match the Action to the Location
Related walkthrough
Collaborative CRM: The Future of Sales Success

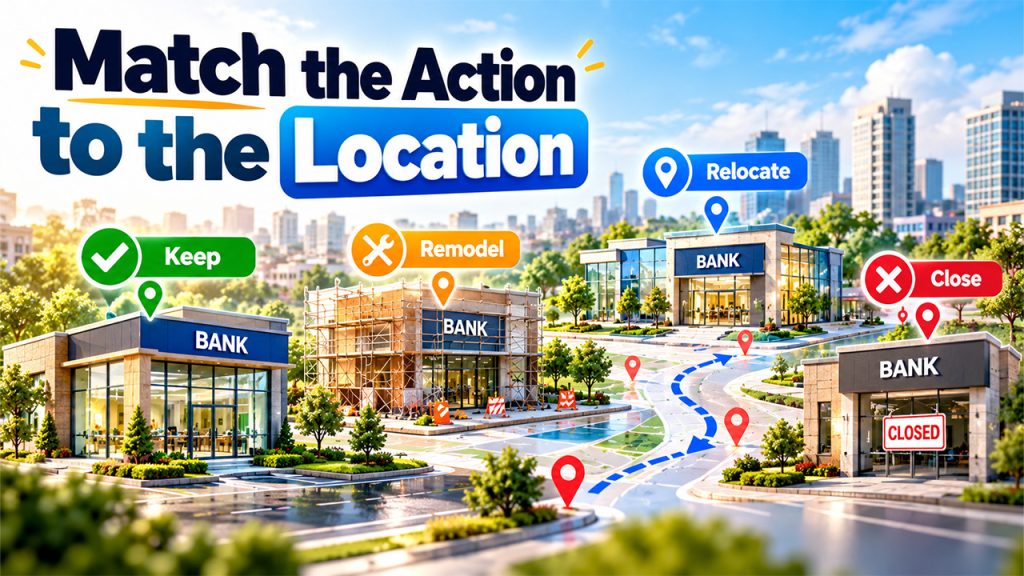
Each location needs a clear recommendation: keep, remodel, relocate, or close. A successful bank branch optimization strategy identifies whether each location should remain open, be remodeled, relocate, or close based on performance and market demand.
The decision should reflect performance, market outlook, and the location’s role in network goals. A remodel suits a viable site whose layout, condition, or service experience no longer meets customer needs. Leaders should first identify the problem, then link proposed work to a measurable service or operating goal.
Relocation makes sense when a branch serves a viable market but its site limits visibility, access, capacity, or an appropriate service mix. Before approving a move, compare nearby sites based on customer travel patterns, local activity, occupancy costs, and future operating needs. Leaders should close a location with weak prospects that harms network performance after assessing customer access and available alternatives.
Connect Decisions to Financial and Operating Plans
Integrating financial projections into a bank branch optimization strategy helps leaders evaluate capital investments, operating expenses, and the long-term impact of network changes.
Financial projections should include the cost and timing of each branch decision, including capital, disruption, and moving expenses. Closures reduce expenses, but they can shift customer demand to nearby branches and change staffing needs. Compare each option over an appropriate planning period instead of treating upfront costs as the full economic result.
The executives should designate specific employees to manage banking workflows, assign responsibilities, and establish dates for the completion of goals. They must document the current numerical data for the actions of the branch, the expenses of operation, the ability of clients to reach the facility, and the quality of assistance. After the staff completes the changes, the executives are able to measure the new data against the original figures. The leaders then modify the number of employees, the hours of operation, or the amount of money they spend. In those records, the managers include the beliefs they held during the planning stage. The evidence helps the reviewers determine if a choice was incorrect or if the conditions of the economy changed in a way they did not predict.
A system of management ensures that the assessments of the branch remain factual after the first choices occur – this structure defines which employees are responsible for subsequent actions. The designated executive is the individual who must authorize significant modifications. At the same time, the local supervisors describe the reactions of clients and the effects on the workflow according to a fixed timetable. The staff uses a single document to monitor the outcomes and the side effects – those effects include the increased distance that clients travel or the high density of individuals inside the facility. The executives are then able to change the strategies before the difficulties with assistance become permanent.
The quarterly meetings ensure that the current data reflects the most recent conditions – those meetings allow the staff members at the branch to describe shifts in the needs of clients. The leaders are able to modify the predictions before they create the next budget for assets. There is a requirement to document the new beliefs and the facts that support them for the following assessment.
Conclusion
Long-term banking success depends on a well-planned bank branch optimization strategy that aligns local market conditions, financial performance, and each branch’s role within the network. The managers are responsible for creating a schedule for assessments. They must record the facts that support every choice and identify the methods for evaluation. Before the executives authorize the closing of a facility, a renovation, a change in location or a decision to spend more money, they must examine how the actions affect the clients and the branches in the same area. A useful action for the executives is to create the initial data points and use them for comparisons.